Mortgage Rates: What You’re Hearing About vs. What You Get

Your actual rate is based on your situation.

With mortgage interest rates crossing the 7% line as a national average you need to remember… 

What you’re reading about or see online is not necessarily the rate you can get.

It’s a common misconception that the rate you see in the headlines is the same one you’d get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about. 

What Determines Your Real Rate? 

Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that. 

That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at:

  • Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate.
  • Your debt-to-income ratio (DTI): This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be.
  • The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage. 
  • The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs. 

Even after you find a home you love, other things can have an impact too. For example:

  • A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy.
  • Seller concessions: Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate. 

There’s a lot that can ultimately have an impact on your actual rate. 

Your First Step? Getting Pre-Approved.

If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be. 

Your lender may recommend a pre-qualification and pre-approval:

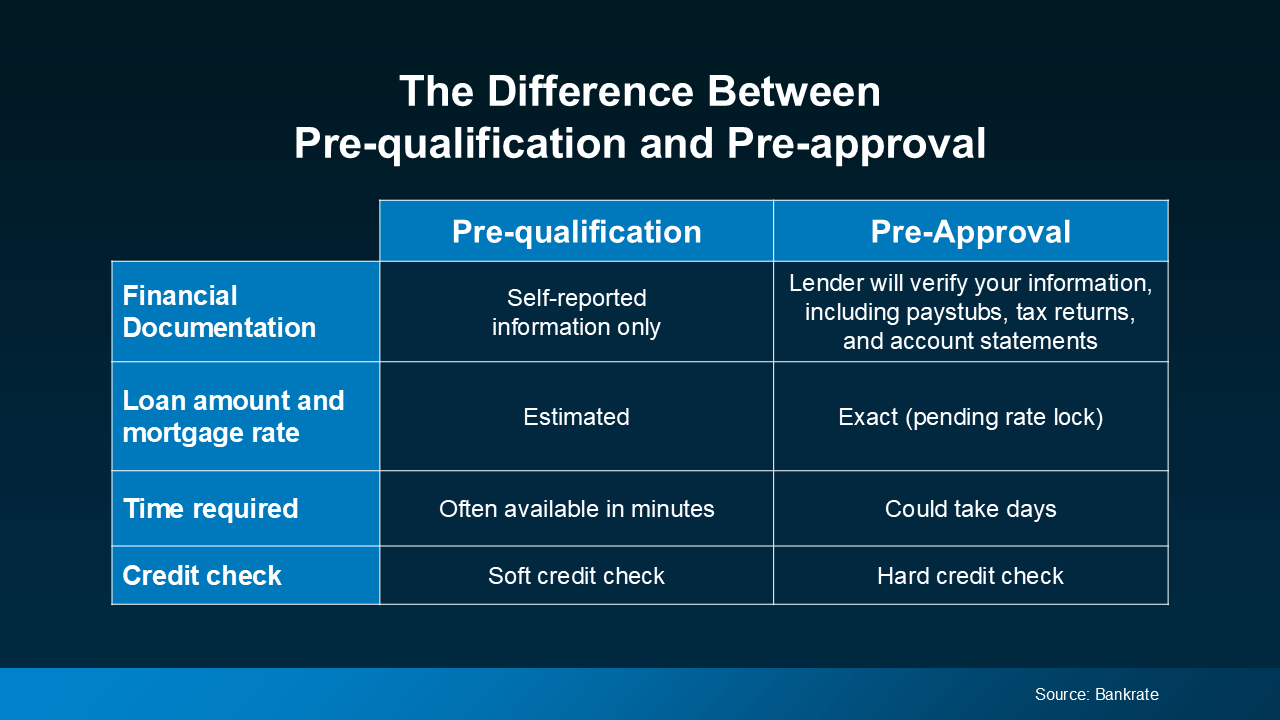
  • Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information. 
  • On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information. 

Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:
a blue and white chart with white text

How To Get Ready for the Conversation

Ask your lender what documents you’ll need to gather for that conversation. And keep these questions in your pocket too. They’re good things to go over when you talk: 

  • What will I gain or lose by waiting to buy a home for 3, 6, or 12 months? 
  • Will I get any tax advantages by buying a home – and what are they? 
  • What’s the benefit of buying a home and starting to build equity now versus waiting? And how does that impact my finances in the long run?
  • How will rate changes in either direction affect me?

Once you find out your rate, maybe you can buy now. Or maybe you still need to wait. But at least you’d know your options and can make an informed decision.  If you need to connect with a qualified lender, please let us know. We can refer you to several who our clients have successfully worked with. 

Bottom Line

Headlines and social media make today’s rates sound high. But you have to remember, the rate you’re seeing online and your actual rate could be different. The only way to know what your rate could be is to talk to a trusted lender. 

With the right help, you can find out what your real rate is – and where it can take you.

Mari, Hank, and Colleen

PS: We were in the Mashpee TV studio late last week with Cape Cod 5 Mortgage Banker Patti Lotane discussing this specific topic. Please watch our social media platforms for links to our “How’s the Market?” program or visit the Mashpee TV website.

Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision.
Mortgage Rates vs. the Spread

Mortgage rates don’t move on their own.

If you’re waiting for mortgage rates to fall significantly before you buy, you may be waiting a while.

But before you get discouraged, there’s a number working behind the scenes that’s actually good for you right now. It’s called the spread, and once you understand it, you may see today’s rates in a whole new light.

The Pattern That’s Held for 50+ Years

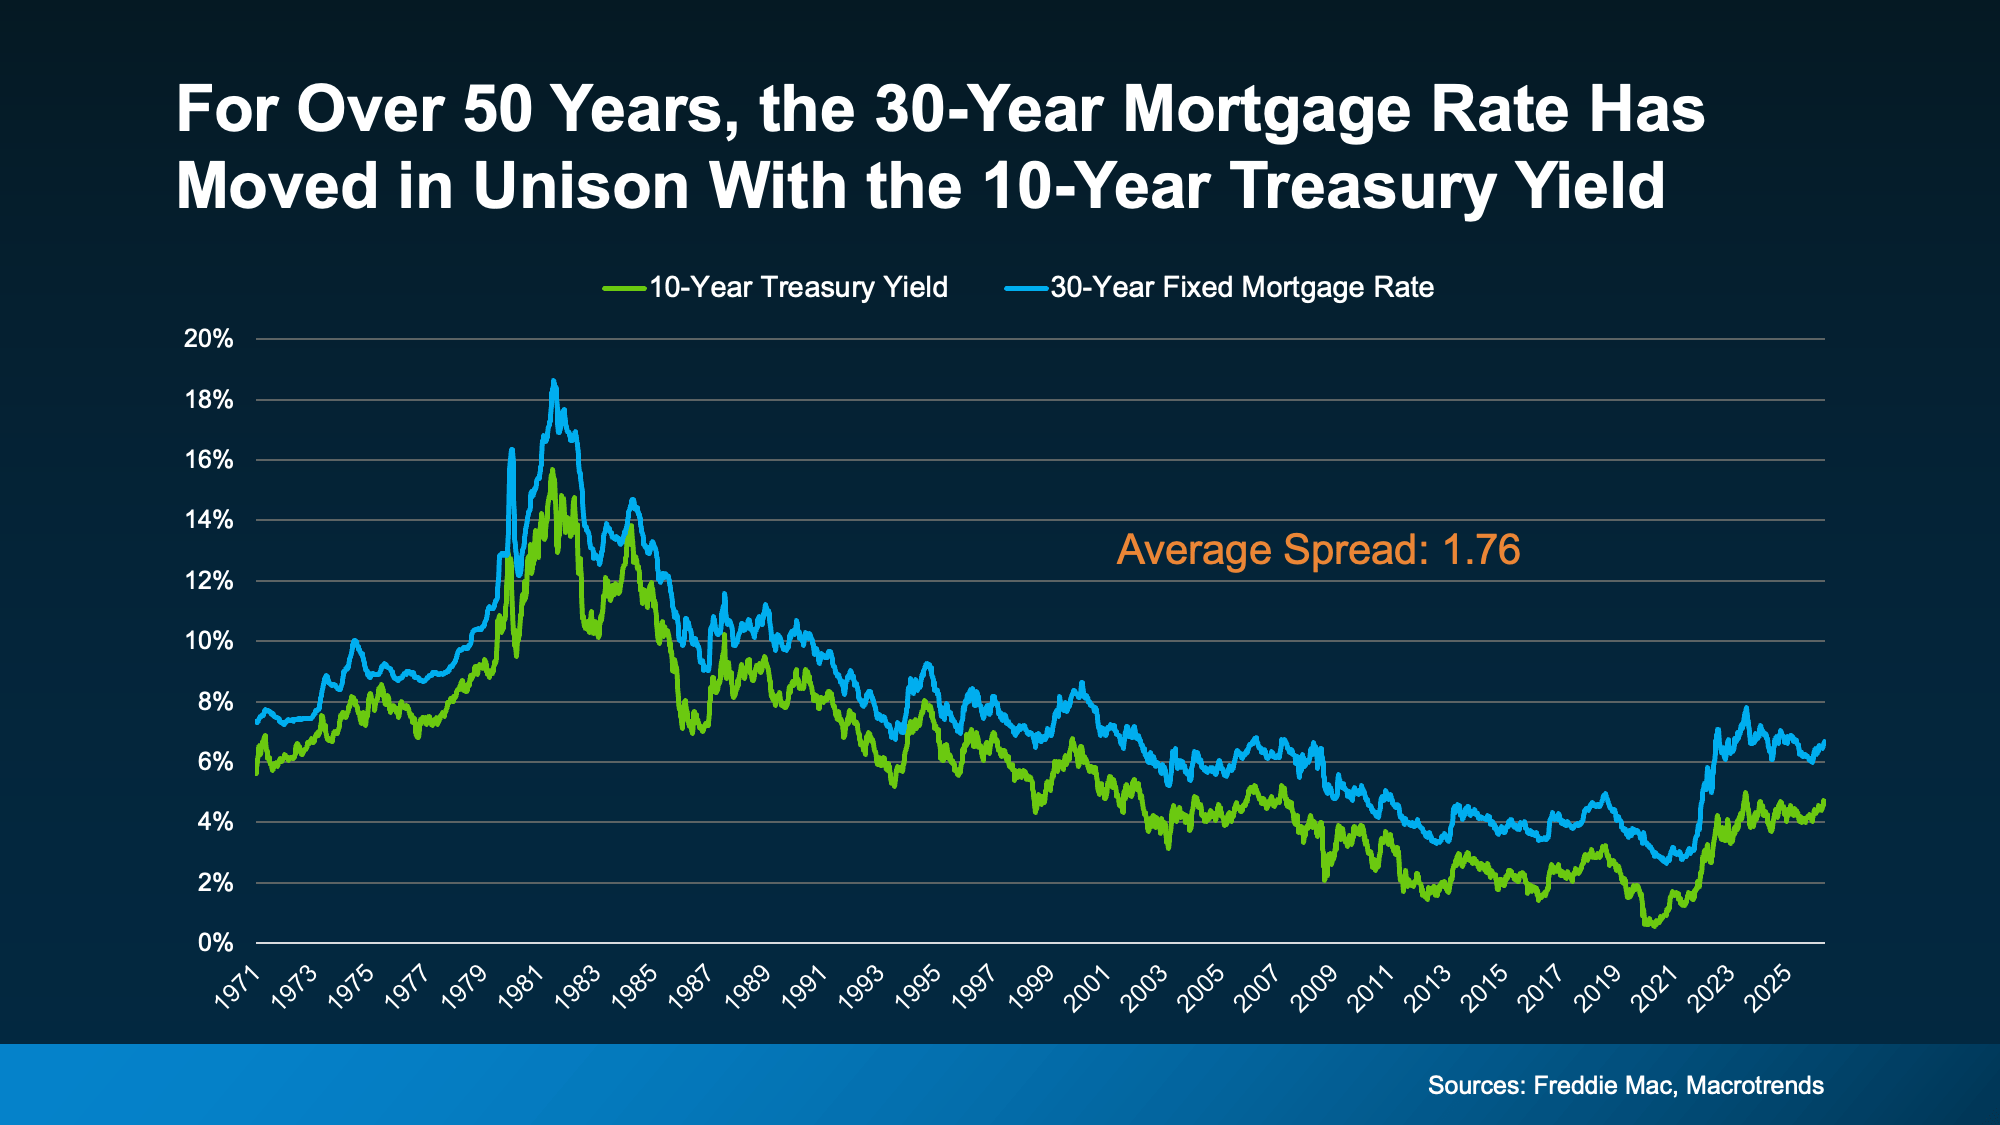
For starters, mortgage rates don’t move on their own. They tend to follow the 10-year treasury yield, a number tied to how investors feel about the economy.

It’s not an exact science, since plenty of other factors can move it day to day. But broadly speaking, when the economy looks strong, that yield tends to climb over time. When the outlook gets shaky, it tends to ease. For over 50 years, the 10-year treasury yield and mortgage rates have moved almost in lockstep (see graph below):

a graph of a graph showing the number of mortgage rates

The gap between them is called the “spread.” On average, that gap runs about 1.76 percentage points. And that spread impacts your mortgage rate. A wider spread tends to push mortgage rates higher than the treasury yield alone would suggest, while a narrower spread keeps rates closer to the treasury yield.

One of the Big Reasons Rates Likely Won’t Drop Dramatically Anytime Soon

If you’re hoping mortgage rates will drop a lot, here’s the reality – they probably won’t. At least not anytime soon. One of the big reasons comes down to that spread between the 10-year treasury yield and mortgage rates.

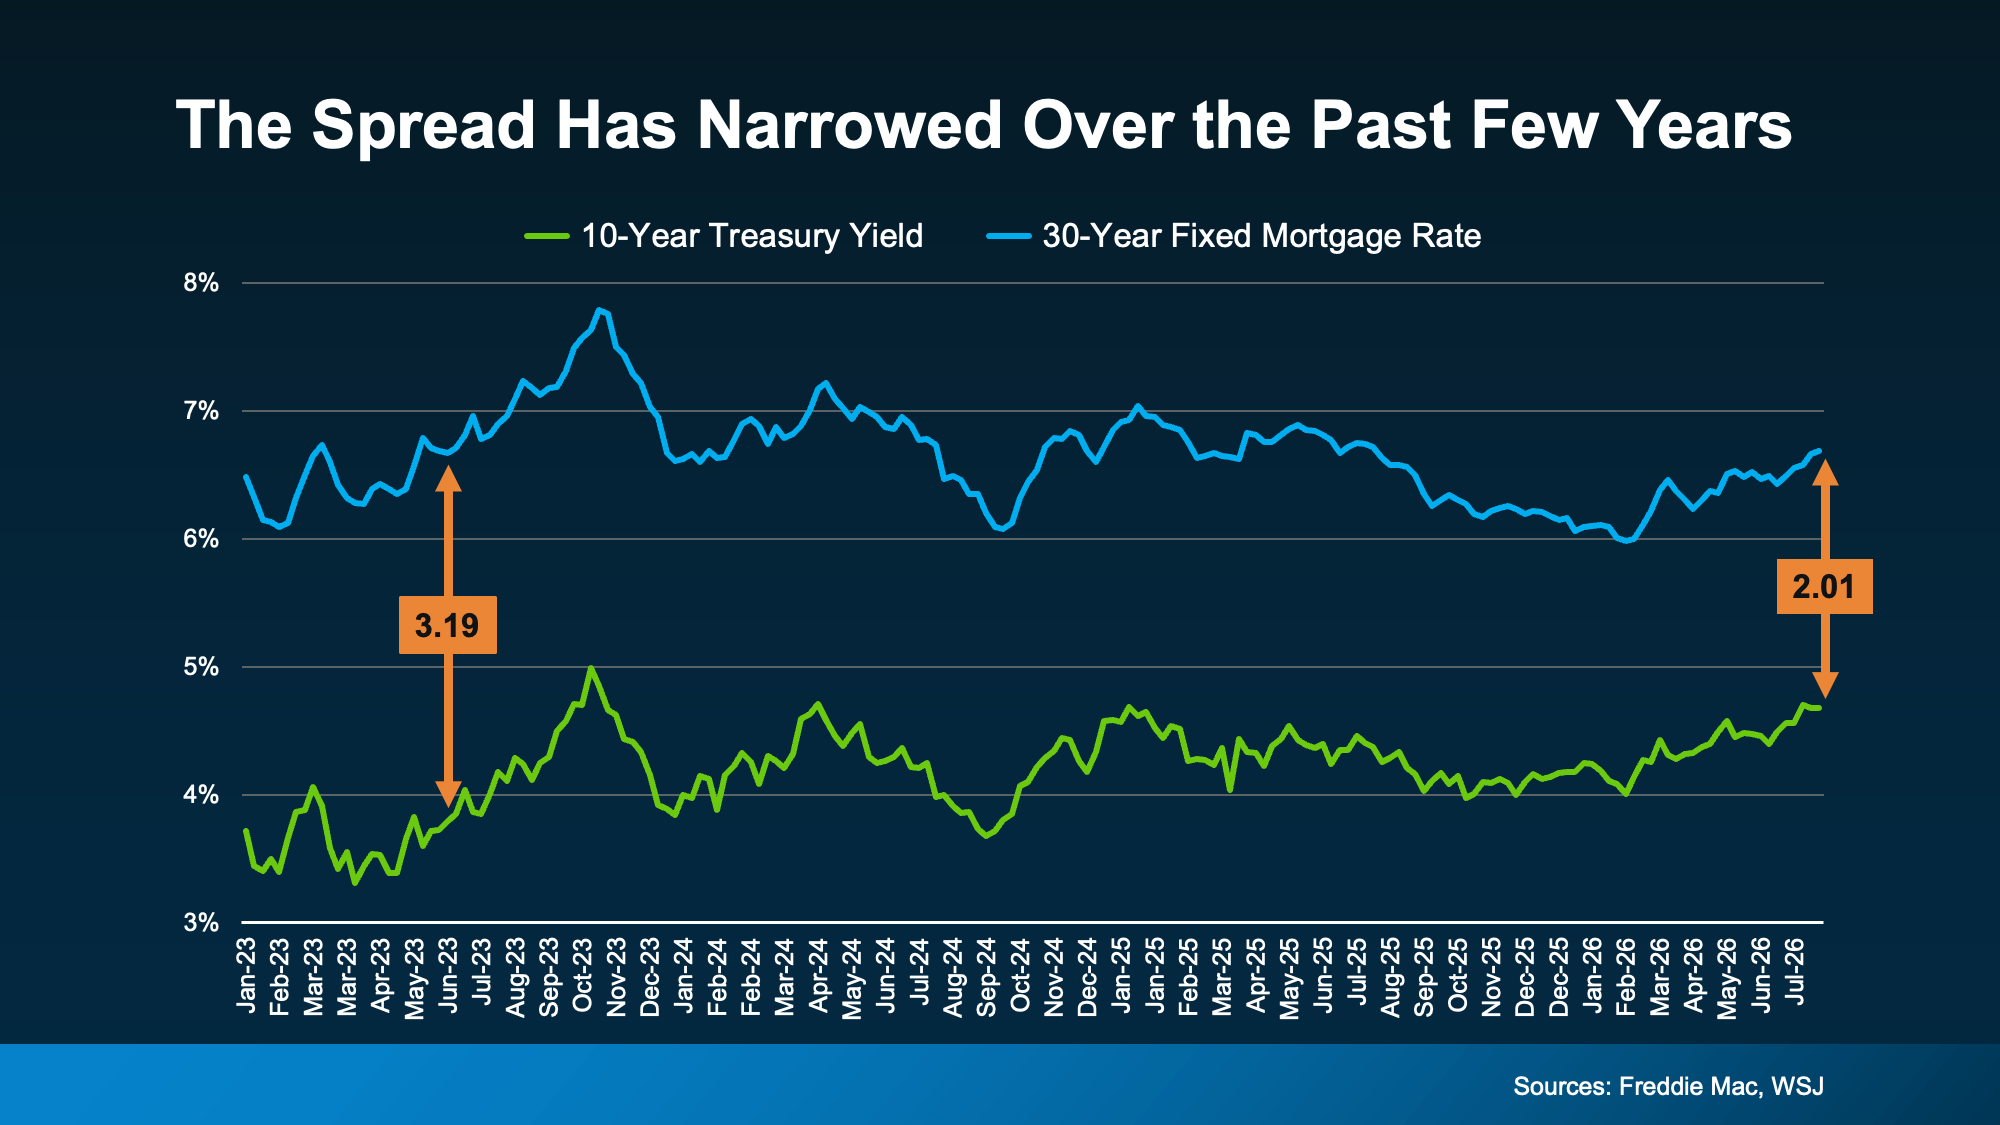
A few years ago, that gap got a lot wider as uncertainty in the economy pushed it as high as 3.19 points in 2023.

Now here’s the part worth noting – that gap has been narrowing lately. It’s down to about 2.01, just above the long-term average of 1.76 (see graph below):

a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of

When the gap is wide, there’s more room for rates to fall. But when it’s relatively normal, like it is now, there’s less wiggle room for rates to fall.

Why Mortgage Rates Aren’t Higher Right Now

Today’s mortgage rate is basically the treasury yield plus the spread. So, when either one moves, your rate moves with it. Here are 3 different rates, all built off today’s 10-year treasury yield of 4.68% to show you just how much the spread matters for your bottom line (see graph below):

a graph of a graph showing a rate of interest

If the spread were still stretched out like it was in 2023, rates would be pushing close to 8% right now. That’s because the spread was over a full point wider than it is today.

But now, thanks to the spread narrowing recently, today’s rate sits around 6.69%. That’s the middle scenario in that visual. That’s a big difference in your monthly payment compared what we could see if the spread was as big as it was 2023.

Now compare that middle bar to the 3rd one. If the spread were sitting at its exact long-term average, rates would be around 6.5%. That’s only about a quarter of a point away from where rates actually are today. That means most of the improvement in mortgage rates we should realistically expect from a shrinking spread has already happened.

In other words, the same narrowing spread that’s the reason rates aren’t close to 8% today is also a big reason why they’re not likely to fall a lot further.

That’s the trade-off with a narrowing spread. Rates may not be where you want them, but they’re better than they could’ve been.

That’s also not what many buyers want to hear, but it’s the fact of life right now.

If you’ve been holding off on the change you know you need to make because of mortgage rates, maybe it’s time to have a serious conversation with a lender to see what your options are. If you need a referral, we’re happy to pass along contact information for some of the outstanding mortgage bankers we work with on a regular basis.

You can always find us at 508-388-1994 (Mari and Hank) and 781-264-5517 (Colleen.) We’re here to help.

Mari, Hank, and Colleen

PS: Please visit our updated website at http://www.makeyourmovewithmari.com. It’s designed to provide you with one place to look whether you’re planning to buy, sell, or are just curious about market conditions. We hope that you find it helpful.

Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision.
Why People Decide to Move

Life doesn’t wait for the perfect market.

You may be telling yourself that you’re going to wait to move – maybe you’re hoping mortgage rates will come down, prices will fall, or the market will feel a little easier.

And honestly? A lot of people are feeling that way right now. But here’s what some are starting to realize.

Waiting doesn’t usually fix the thing that made you want to move in the first place.

Your family still desperately needs more room. Your empty nest still feels too…empty.

Your parents or grandparents still need you to live closer.

You just got married… or divorced.

Your vision of retirement has you living somewhere else.

Eventually, life can reach a point where waiting feels harder than moving.

That’s why some people are still deciding to buy right now, even in today’s market. Not because conditions are perfect. But because the life changes behind their move never really went away.

And maybe that’s exactly where you are too. If so, you’re certainly not alone.

The Real Reasons People Move 

Data from the National Association of Realtors (NAR) shows 1 in 5 buyers last year said they felt like they had to purchase a home at that time, no matter the market.

That’s an important reminder right now. Sure, the dollars and cents of your move have to make sense for you. But big life changes happen whether mortgage rates and home prices are high, low, or somewhere in between. 

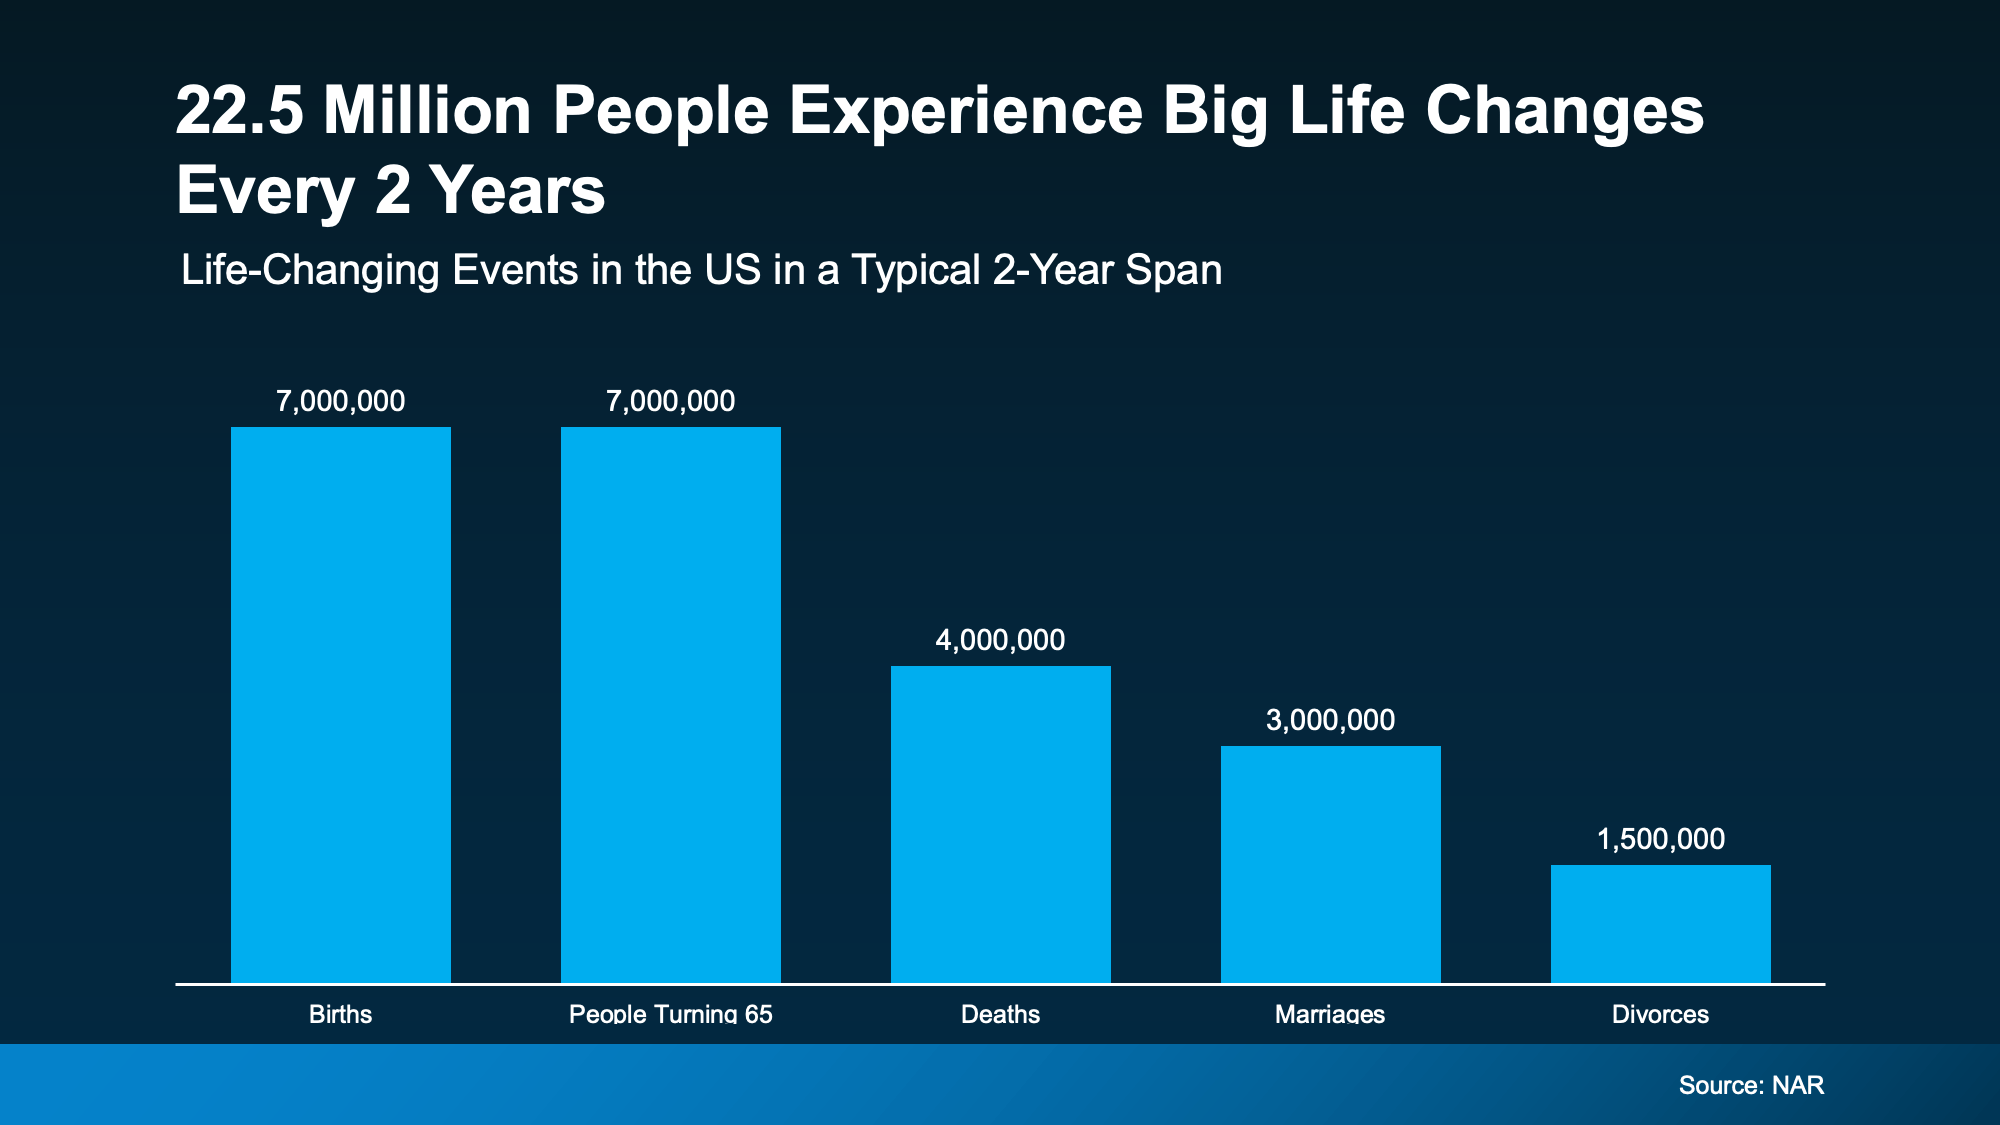
And those big life events happen more than you may think. NAR says roughly 22.5 million people experience major life changes in a typical two-year span (see graph below):

a graph of blue rectangular objects

These are exactly the kinds of things that can change how much space you need, where you want to live, or what kind of lifestyle makes sense now. Chen Zhao, Head of Economics Research at Redfin, explains:

“Life doesn’t stand still—people get new jobs, grow their families, downsize after retirement, or simply want to live in a different neighborhood.”

And that’s what makes waiting so hard. Every month you spend hoping the market changes is another month living in a house that no longer works for your life. It’s stressful to feel stuck. And that feeling usually doesn’t disappear.

There May Be More Opportunity Than You Think

But while affordability is still a challenge, there may still be a way for you to make your move.

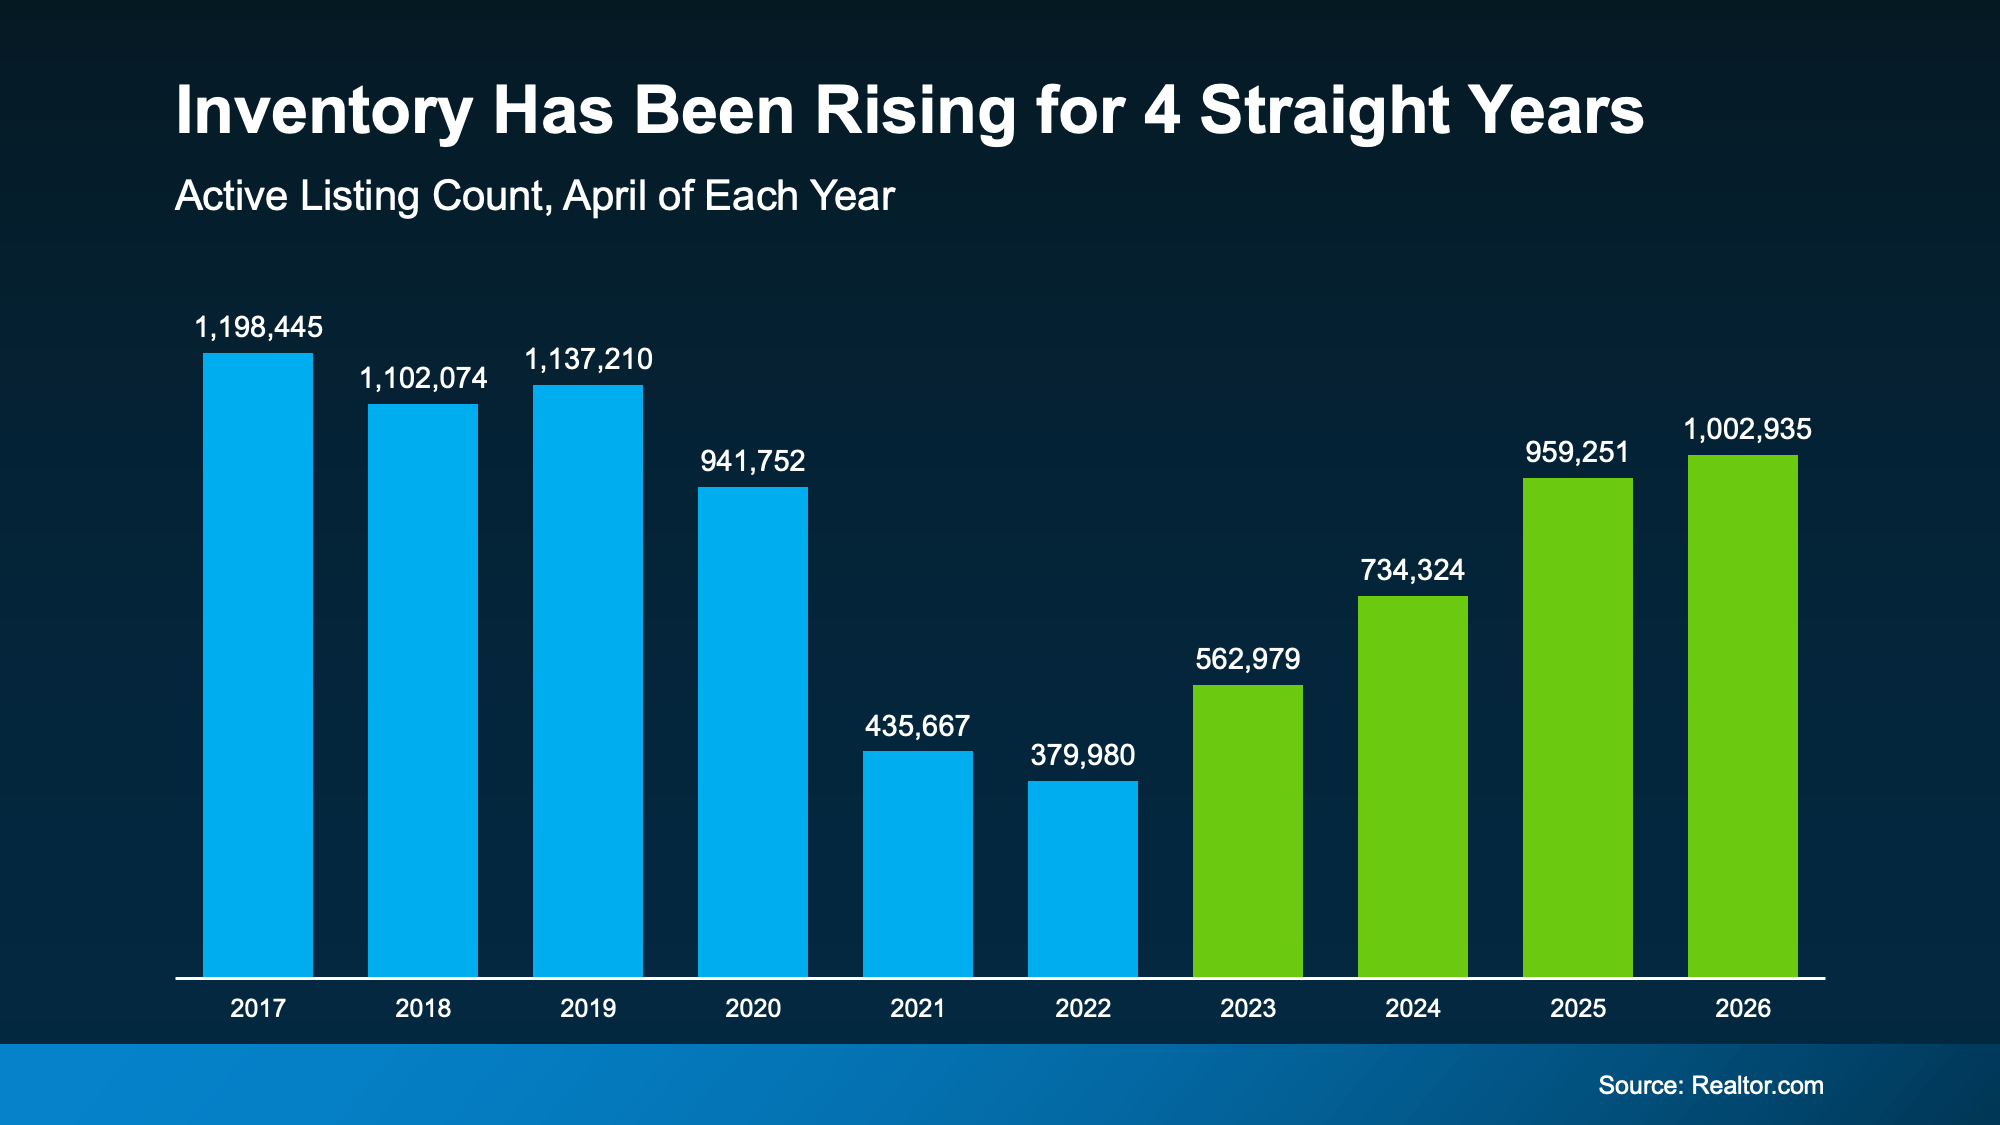
The number of homes for sale has been growing for 4 straight years (see graph below). That means more homes to choose from, and, in some markets, more room to negotiate than buyers had just a few years ago. 

a graph of growth of a straight year

That doesn’t mean moving is suddenly easy. But it does mean some buyers are finding ways to make a move work. So, if you’ve been putting your plans on hold, maybe the question isn’t just:

“What’s the market doing?” or “When will it get better?”

Maybe ask yourself this, too: “Can I still live where I’m at right now and make it work?”

If the answer to that second question is “no,” it may be worth having a conversation about what your options look like today – despite where rates or prices are. You could find your move is still possible after all. With more homes for sale, there’s a better chance to find one that fits your life (and your budget) right now.

Bottom Line

Life changes. Priorities shift. Families grow. Kids move out. Careers evolve. And eventually, the house you’re in may stop fitting the life you’re living.

If that’s been weighing on you lately, let’s talk through what your options could realistically look like today, no matter where rates or prices are. You can always find us at 508-388-1994 (Mari and Hank) or 781-264-5517 (Colleen).

Life can’t always wait for perfect market conditions. Maybe you don’t have to either.

Mari, Hank, and Colleen

Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision.
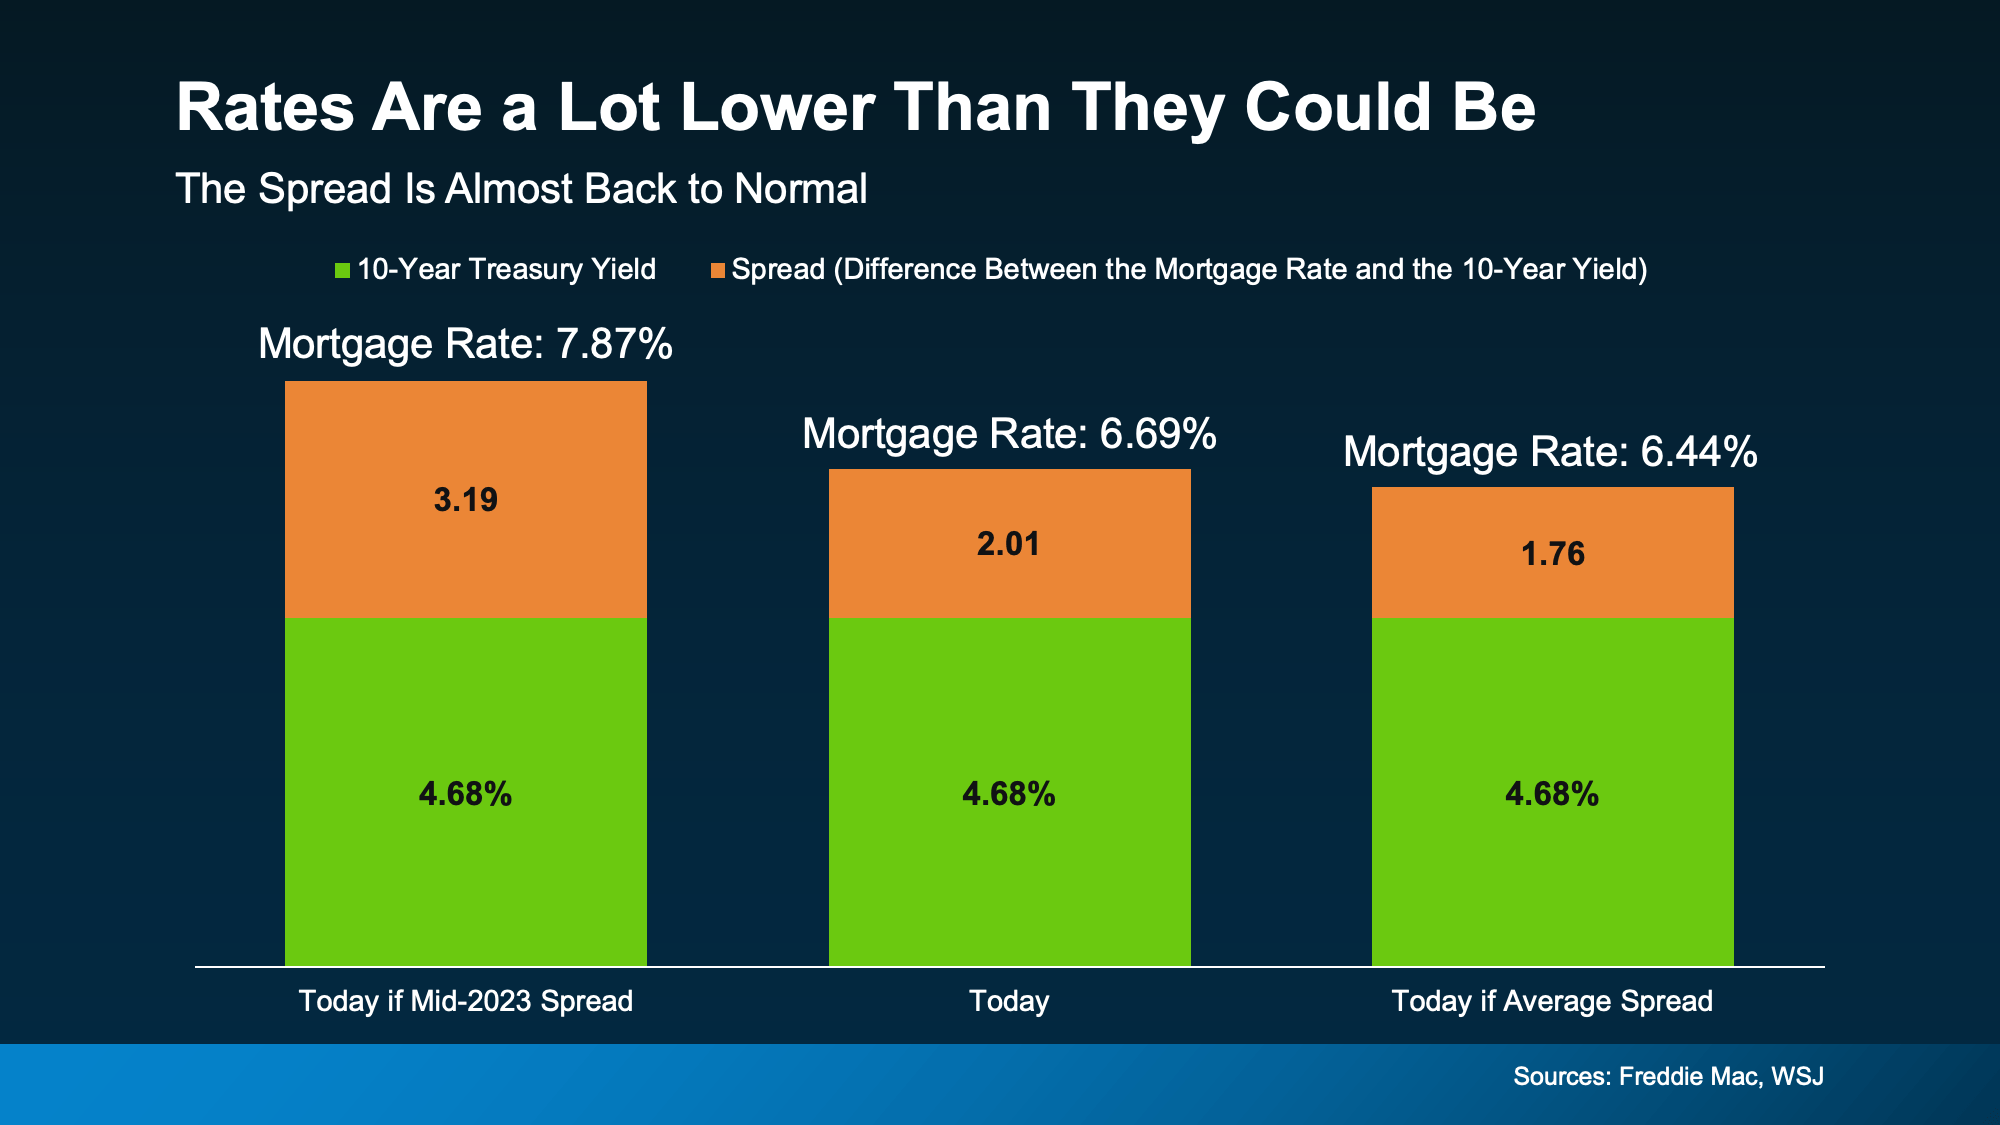
11,000 Homes Sell Every Day. When’s Yours?

Are you hesitant to sell your house because you’ve heard that no one is buying with rates and prices where they are right now? Here’s some perspective that should help.

The market isn’t at a standstill. While there weren’t as many sales last year as there’d be in a normal market, roughly 4.15 million homes still sold (not including new construction), according to the National Association of Realtors (NAR). And the expectation is that number will rise in 2025. That means more people will likely move this year, and they need homes to buy homes like yours.

But even if we only match last year’s sales pace, here’s what that looks like.

Every Minute Homes Are Selling – Literally

  • 4.15 million homes ÷ 365 days in a year = 11,370 homes sell each day
  • 11,370 homes ÷ 24 hours in a day = 474 homes sell per hour
  • 474 homes ÷ 60 minutes = roughly 8 homes sell every minute

Think about that. Just in the time it took you to read this, 8 homes sold.

On Cape Cod, home sales are up 6.8% for 2024. through November. End of the year stats should be available soon.

If you’ve been holding off selling your house because you think buyers aren’t out there, let this reassure you – there are still buyers looking to buy.

While higher home prices and mortgage rates have slowed down the market and forced some buyers to the sidelines, that doesn’t mean the market isn’t active. Many buyers are still eager to make a move because life doesn’t wait for “perfect” market conditions. (And as we wrote about last week, time in the market is a more sensible strategy than trying to time the market.)

Every day, thousands of people need to buy homes. Life goes on no matter what interest rates or prices are. People get new jobs or are transferred. Some get married and can’t keep living in their parents’ basement. Others have children and need more space.

Let’s talk. We can get your house in front of buyers while other hesitant homeowners are still pausing their plans because they think buyer demand has disappeared. Let’s work together to get your house sold.

Mari and Hank

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision.